Demystifying IPOs for the next generation

November 05, 2026
  • Capital Partners
What does it take to evaluate a company before it enters the public markets? And what can a high-profile IPO like SpaceX teach investors about opportunity, risk, and valuation?

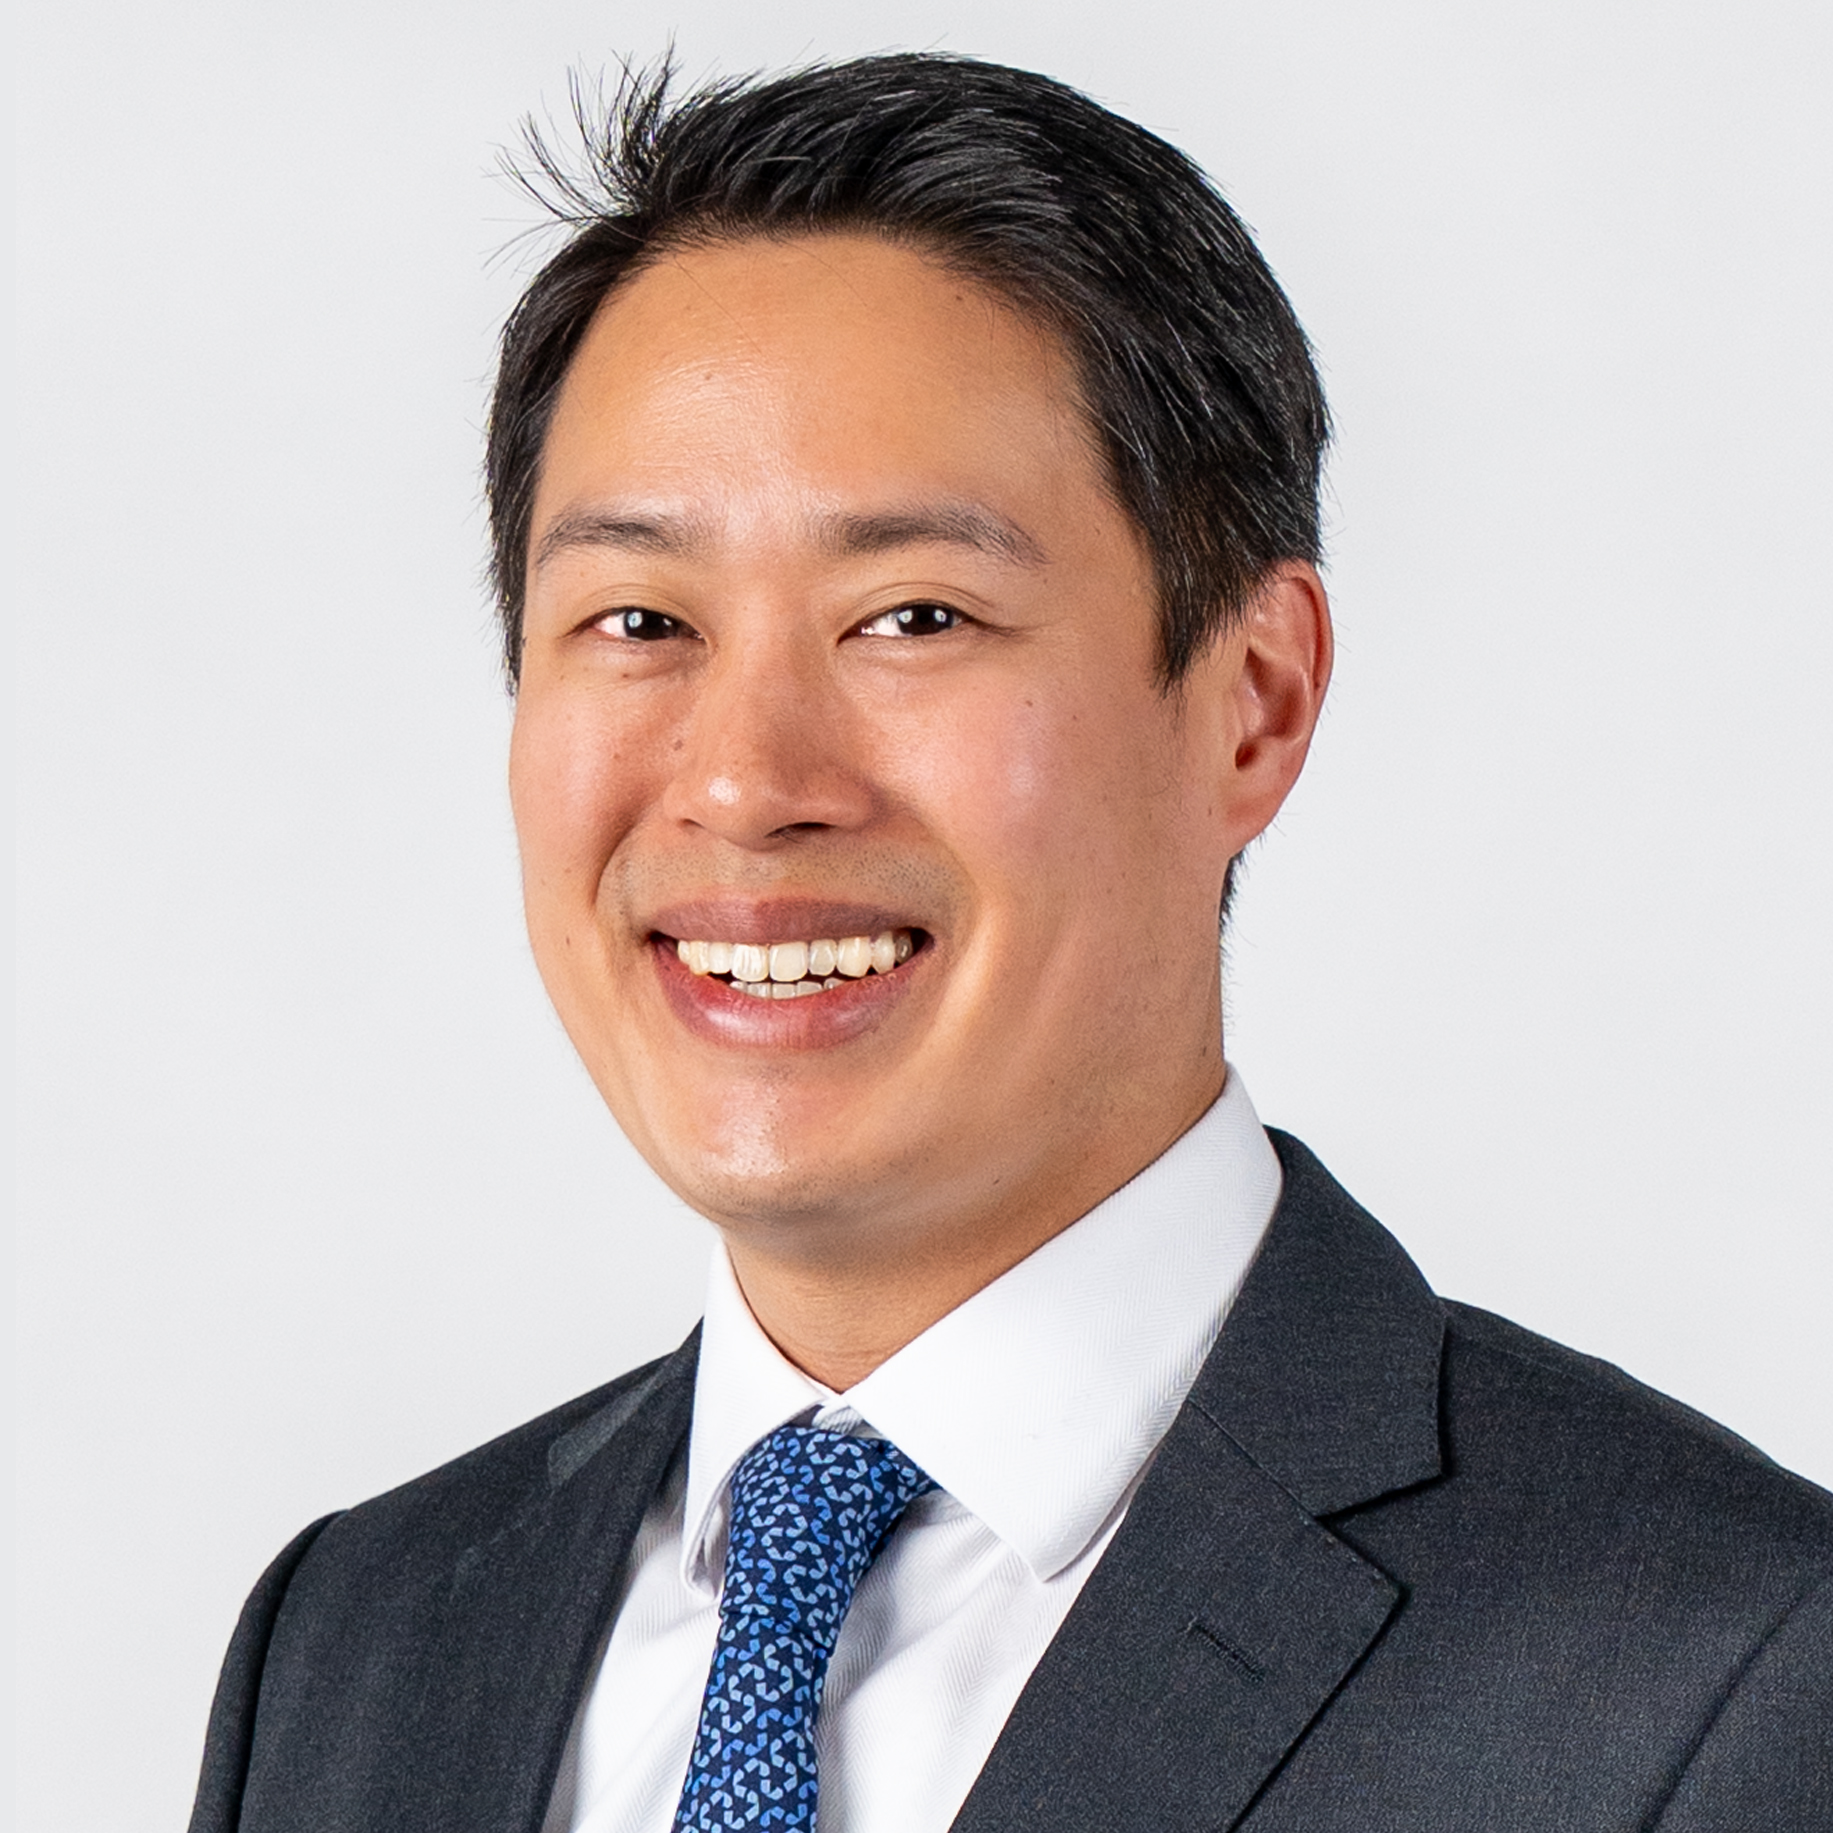
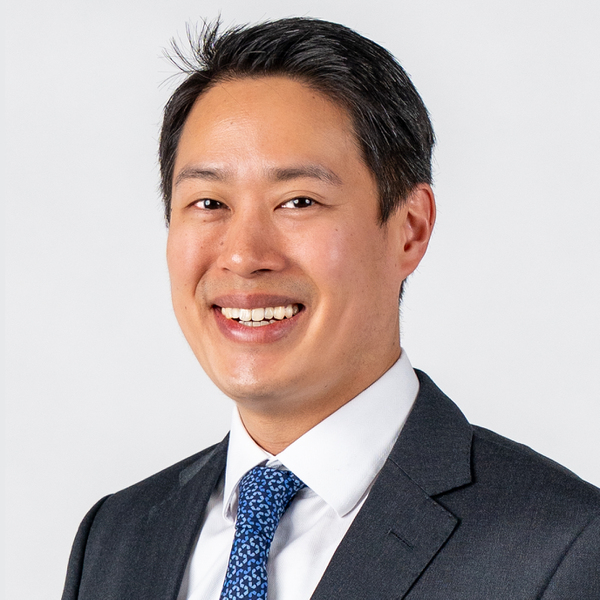
In this edition of The Fresh Take, Owen McCarthy sits down with Eric Yeh to discuss how we evaluate initial public offerings (IPOs), what investors should look for in a company’s S-1 filing, and what can a high-profile IPO like SpaceX teach investors about changing industry dynamics, opportunity, risk, and valuation.

Owen McCarthy: How do we evaluate IPOs, and how does that compare with our typical investment underwriting process?

Eric Yeh: Our fundamental approach to evaluating IPOs is consistent with our broader investment underwriting process. We start by evaluating businesses against our qualitative framework, which prioritizes companies that:

  • Provide essential products and services
  • Lead attractive markets
  • Have high levels of customer loyalty
  • Maintain sustainable competitive advantages

For companies that meet these criteria, we evaluate the quality of the management team. We believe management should be aligned with shareholders’ interests and demonstrate prudent stewardship of shareholder capital.

From a quantitative perspective, we look for businesses that generate high, sustainable returns on invested capital and have opportunities to reinvest in the business to grow free cash flow per share.

IPOs also present some unique considerations compared with established public companies. They often have shorter financial and operating histories, are at earlier stages of maturity, and have management teams with less experience running a public company or communicating with public shareholders. Other factors include governance structures, such as multiple classes of shares with different voting rights, and technical factors that can affect trading after the IPO, including lock-up periods, potential selling pressure from existing shareholders, and a limited number of shares available to trade.

We consider all these IPO-specific factors alongside our broader qualitative and quantitative underwriting process.

OM: Why does SpaceX stand out, and how did we evaluate the IPO?

EY: SpaceX is unique in its scope, scale, and ambitions. Its IPO was consequential not only because of its size, but also because of the potential impact the company could have across multiple industries if management executes on its vision.

SpaceX operates three primary businesses: Space, Connectivity, and AI. Its Space and Connectivity businesses are pioneers that have helped create and reshape their respective industries. They have established leading market positions, sustainable competitive advantages, and attractive growth opportunities.

The scale and ambition of SpaceX’s AI business are also unprecedented. Its plans include rapidly expanding terrestrial AI computing infrastructure, developing orbital computing capabilities, and building a semiconductor foundry that could rival the industry’s largest players. If successful, these initiatives could reshape competition and industry structures across the technology ecosystem, with significant implications for our technology investments and the broader market.

To evaluate SpaceX, we assessed each business segment against our qualitative and quantitative criteria. Our diligence included reviewing public filings, speaking with the underwriting banks, conducting industry research, and meeting with management.

We also considered several IPO-specific factors that could significantly influence trading, including:

  • Chairman and CEO Elon Musk’s approximately 49% economic ownership and 84% voting power
  • A limited public float, with less than 5% of shares outstanding available to trade at the IPO
  • Demand that far exceeded the number of shares available, with the order book multiple times oversubscribed
  • A fixed IPO price despite strong demand
  • A significantly higher-than-usual allocation to retail investors
  • A nonstandard lock-up structure that allowed certain shares to be released earlier than is typical
  • The potential for accelerated inclusion in certain stock market indices
For more details on our evaluation of SpaceX and similar companies, please reach out to a BBH Relationship Manager.

OM: When reading a company’s S-1 filing, what should investors look for beyond the headline numbers?

EY: As noted, we paid close attention to factors such as Elon Musk’s economic ownership and voting power, the number of shares available to trade after the IPO, and the lock-up structure. More broadly, investors should look beyond the headline financials and understand:

  • Business performance: What is driving the company’s results, and how have its operations and financial performance changed over time? The Management’s Discussion and Analysis (MD&A) section is a good place to start.
  • Key performance indicators: How does management measure success, and how have those metrics trended?
  • Management incentives: Is the compensation structure aligned with shareholders’ interests?
  • Unit economics: How profitable are individual products, services, or business segments, and what might that mean for the company’s long-term earnings potential?
  • Market opportunity: How does management define and estimate the size of its addressable market?
  • Risks: What could go wrong, and what steps is the company taking to mitigate those risks?

Every IPO is different, and the factors investors should prioritize will depend on the company and its circumstances.

Every IPO is different, and the factors investors should prioritize will depend on the company and its circumstances.”


OM: SpaceX shares initially rose 19% above the $135 IPO price before falling as much as 23% from their post-IPO high. What does that tell us about how markets are responding to large tech and AI-related IPOs?

EY: Many factors influence how an IPO trades, so it is difficult to draw broad conclusions about the technology IPO market from one company’s stock price alone. In SpaceX’s case, the initial jump and subsequent volatility did not particularly surprise us, given the trading dynamics discussed earlier: a limited public float, a fixed IPO price, an oversubscribed order book, a significant retail investor allocation, and a nonstandard lock-up structure. At a high level, strong demand for the IPO signaled that capital markets remain willing to fund the buildout of AI infrastructure.

From a fundamental perspective, most of SpaceX’s value is attributable to its AI business, which is also its least mature business. Much of that value depends on what the business could become over the long term, rather than on its current results. That makes SpaceX’s valuation particularly sensitive to near-term performance and changing expectations. Even incremental updates that differ from what investors anticipate can have an outsized impact on the stock price.

OM: More companies are raising substantial amounts of private capital before going public. Has that changed how we evaluate IPOs, and are these companies more mature than traditional growth businesses?

EY: The increasing size and liquidity of private markets have not changed our fundamental investment underwriting framework. However, the growth of private companies can have a significant impact on competition, industry dynamics, and our portfolio companies.

This is especially apparent in technology, where private companies often drive innovation and disruption, creating the next generation of market leaders and sometimes displacing established public companies. That is why we believe technology investors need to stay closely attuned to the private company ecosystem, whether or not they invest directly in private companies or IPOs. Our investment team often spends considerable time researching and meeting with private companies to understand how they may affect the competitive landscape for current and prospective investments. Larger private companies can sometimes offer more operating history and data to evaluate when they go public. For example, SpaceX’s Space and Connectivity businesses had several years of operating history, giving us greater visibility into their unit economics and longer-term trends.

But scale does not necessarily mean maturity. SpaceX’s AI business is still in its early stages following the acquisition of xAI in the first quarter of 2026, and much of its valuation depends on an ambitious, largely unproven roadmap. Similarly, Anthropic was founded in 2021, and its business model continues to grow and evolve despite the company’s scale.

Ultimately, we would not assume that companies staying private longer are necessarily more mature when they go public. Each situation is different, and some private companies are achieving rapid growth at significant scale while their businesses continue to evolve.

Each situation is different, and some private companies are achieving rapid growth at significant scale while their businesses continue to evolve.”


OM: Every generation has its defining IPOs, from Facebook and Uber to today’s potential market leaders, SpaceX and Anthropic. Do these companies feel different, or are we seeing familiar patterns?

EY: There are similarities between past high-profile IPOs and the current generation. Facebook and Uber were leaders in markets they helped pioneer and define. Both faced investor debates about their valuations and unit economics. Facebook also faced questions about the risks of shifting its business from desktop to mobile.

SpaceX and Anthropic are similarly viewed as pioneers and leaders in their respective industries, and investors continue to debate their valuations, unit economics, and evolving business models. However, there are important differences, particularly in scale, as both companies would rank among the top 10 S&P 500 companies by market capitalization based on their current or expected valuation.

SpaceX and Anthropic are two highly consequential companies in the AI ecosystem, with potential implications for both technology and the broader market. Both are major customers and competitors of several of our portfolio companies, meaning their performance and strategic decisions can have substantial impacts across the businesses we follow.

At the same time, technology companies, and AI investment in particular, are driving an increasing share of earnings growth across the broader market. The degree to which the market depends on a relatively small group of private and recently public companies is unprecedented. That interconnectedness is something we will continue to monitor closely as we evaluate investment opportunities and the risks facing our portfolio companies.

Stacks of gold coins on a desk in a modern office with cityscape view
Up Next
Up Next

Private credit for the next generation: What it is and why it matters

Private credit is one of the fastest-growing corners of investing — and one of the most misunderstood. Here's what it actually is, why it's in the headlines, and where we see real opportunity.

References to specific securities, asset classes, and financial markets are for illustrative purposes only and are not intended to be and should not be interpreted as recommendations.

Brown Brothers Harriman & Co. (“BBH”) may be used to reference the company as a whole and/or its various subsidiaries generally. This material and any products or services may be issued or provided in multiple jurisdictions by duly authorized and regulated subsidiaries. This material is for general information and reference purposes only and does not constitute legal, tax or investment advice and is not intended as an offer to sell, or a solicitation to buy securities, services or investment products. Any reference to tax matters is not intended to be used, and may not be used, for purposes of avoiding penalties under the U.S. Internal Revenue Code, or other applicable tax regimes, or for promotion, marketing or recommendation to third parties. All information has been obtained from sources believed to be reliable, but accuracy is not guaranteed, and reliance should not be placed on the information presented. This material may not be reproduced, copied or transmitted, or any of the content disclosed to third parties, without the permission of BBH. All trademarks and service marks included are the property of BBH or their respective owners. © Brown Brothers Harriman & Co. 2026. All rights reserved. PB-10010-2026-10-29

As of June 15, 2022 Internet Explorer 11 is not supported by BBH.com.